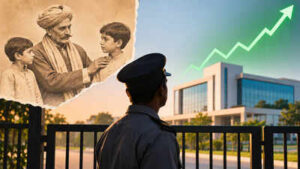
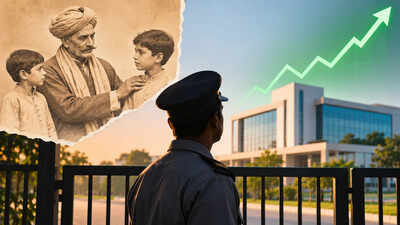
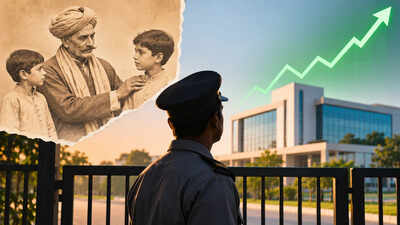
At IIT Delhi this week, the investor Gaurav Dalmia gave students twelve stories about how wealth gets made. The one that stays with you is about how easily it could have gone to someone else.Some years ago, Rajiv Bajaj was in Sikar, Rajasthan, in his great-grandfather’s village, filming a documentary about his family. In the crowd he noticed a familiar face: a watchman from Bajaj Auto. Bajaj asked what he was doing there. The man said that this was home. His family and the Bajajs had been neighbours.The two families’ fortunes parted over one decision. In 1894, a wealthy merchant named Seth Bachhraj adopted a small boy from the area, Jamnalal, to raise as his grandson and heir. Bajaj, telling the story later, thanked his luck, and wondered what would have followed had the merchant chosen the boy next door. The watchman’s family might be running the company. Rajiv Bajaj might be the one on duty outside.Gaurav Dalmia told this story on Wednesday evening to the Economics and Finance Club at IIT Delhi. He placed it at the end of his first case study, almost as an aside. A room of students hoping to make their fortunes could be forgiven for hearing a charming digression. I think it was the most serious thing he said.Dalmia chairs Dalmia Group Holdings, which invests in private equity, property and public markets. I know him as a man who reads constantly and would rather talk about what he has read than about what he owns. His title for the evening could not have been drier: “Indian Business Landscape: Select Case Studies.” There were twelve companies, most of them Indian, and most came with the same kind of chart, drawn on a log scale.A log scale is an unromantic thing. Each equal step up the page means the number has multiplied by the same amount, so a rise from 1 to 2 takes up as much room as a rise from 1,000 to 2,000. The drama of any given year shrinks. What remains is the rate of growth, held over decades. Look at enough of these charts and you begin to see business the way Dalmia seems to: slowly, and in ratios.He began with a man being wrong. In 1991, India’s foreign reserves had fallen to about $1 billion, barely two or three weeks of imports, and the country opened up because it had little choice. Rahul Bajaj and the so-called Bombay Club asked for a gradual shift, fearing that Indian companies would be crushed before they could adapt. Dalmia’s verdict took one sentence: Bajaj was wrong. Since 2002 alone, Bajaj Auto’s revenue has grown almost 16-fold and its market value about 50-fold, or roughly 100-fold counting the spun-off Bajaj Finserv. The company whose patriarch feared foreign competition now sells in a hundred countries.Then came the long stretches when nothing seems to pay. Nvidia, today worth some $5 trillion, is now spoken of as destiny. By Dalmia’s count, between 2004 and 2008 its profits rose more than 16-fold while its market value rose only 3.6 times, and in one year profits jumped 82 per cent while the stock did not move. Such years, he noted, weigh on a chief executive. Infosys, whose market value has gone from Rs 191 crore in 1994 to more than Rs 5 lakh crore, makes a related point: private equity firms often sell at listing, assuming the best years are over, and the people who buy from them often find that the party has just begun.Berkshire Hathaway supplied the arithmetic. A thousand dollars in 1965, compounding at the S&P 500’s 10.6 per cent with dividends, became about $455,000. In Warren Buffett’s company, at 19.8 per cent, it became nearly $61 million. You would hardly have noticed the gap in the first five years. And from 2020 to 2025, in the age of the technology stock, Berkshire beat the Nasdaq, 2.2 times to 1.8. “Many techies will find this very humbling,” he told a room at an IIT.His second habit is a distrust of categories. Lakshmi Mittal, short of capital in his early years, bought the failing steel mills that bigger companies would not touch, the “hairy assets,” at less than it would cost to build them new, starting with a loss-making plant in Trinidad and Tobago. His fortune went from $1.5 billion in 1996 to $45 billion in 2008. Varun Beverages, the Pepsi bottler, was Dalmia’s example of how an old Western business can be a young Indian one. If wages are growing 9 to 11 per cent a year, he argued, then what millions of Indians have left after roti, kapda aur makaan is growing at 20 per cent or more. Fizzy drinks follow. Varun’s annual profit went from Rs 42 crore in 2016 to more than Rs 3,000 crore.Cement is a dull commodity, unless you are Aliko Dangote in Nigeria, where poor infrastructure keeps competition out and a tonne earns about $24 in profit, against about $6 for India’s UltraTech. A car company is a low-margin grind, unless you are Ferrari, which holds production to about 14,000 cars and barely advertises. Its revenue is about $8 billion, against Volkswagen’s $364 billion. Its market value is larger than Volkswagen’s. An industry, in Dalmia’s telling, is an average, and averages hide the interesting people.The third thing he looks for is harder to chart. Dalmia invested early in the lender Incred in 2017, so he is hardly neutral about it, and he says that what drew him was the absence of a certain quality. Non-bank lending was then the flavour of the month. Plenty of founders were raising money on the trend with little of their own at stake, a free bet on someone else’s capital. He calls this “bubble bravery,” and it is a phrase worth carrying into any funding boom, including the present one. Incred’s founder put in serious money of his own.He also tried to rescue an unloved word. Growth, he told the future founders, needs both innovation and bureaucracy, by which he meant not sloth but procedure: the discipline of running something at scale once the experiment has worked. And what, he asked, is the true price of building a global business? Not money, not great products, not fine management. Jet lag.There is an objection to all this, and the talk’s opening story supplies it. Twelve winners are twelve survivors. There was no chart for the many lenders of 2017 that, by his own account, did not do well, and no slide for the distressed mill that stayed distressed. The hardest claim came last. Describing Adani Green’s vast renewable park at Khavda in Gujarat, on land the state allotted to six developers, Dalmia argued that outsiders overrate government relations and that the real value lies in getting the project built. Adani’s speed is on the record: ground broken in 2023, 4.1 gigawatts by the end of 2025. But a sceptic might say that one does not rule out the other. The transcript stops where the questions begin, so I cannot say whether anyone in the room took that up.
Share your thoughts in the comments
Be respectful · TOI community guidelines
To his credit, he marks the edges of his own certainty. He flags that his view of Infosys comes from before any disruption by AI. He reads Berkshire’s cash pile of some $350 billion as a warning about frothy markets, then adds that time will tell. Having praised Buffett at length, he tells students to read George Soros, who holds nearly the opposite view of markets, as a balance. People selling a system rarely recommend its rival.His last word to the students was junoon. Passion, he said, is what he has seen matter more than anything else, time after time. It is a fine thing to tell twenty-year-olds, and I expect it is true. But he had also told them about Sikar, and he left the two stories side by side without trying to reconcile them. I am not sure they can be reconciled. Every line on his charts starts after somebody has already been chosen. No log scale can show the morning in 1894 when a merchant looked over two neighbouring families and picked one. Or the watchman, more than a century later, still on duty.